Can I Buy a Condo in Dallas, Fort Worth With FHA Financing?
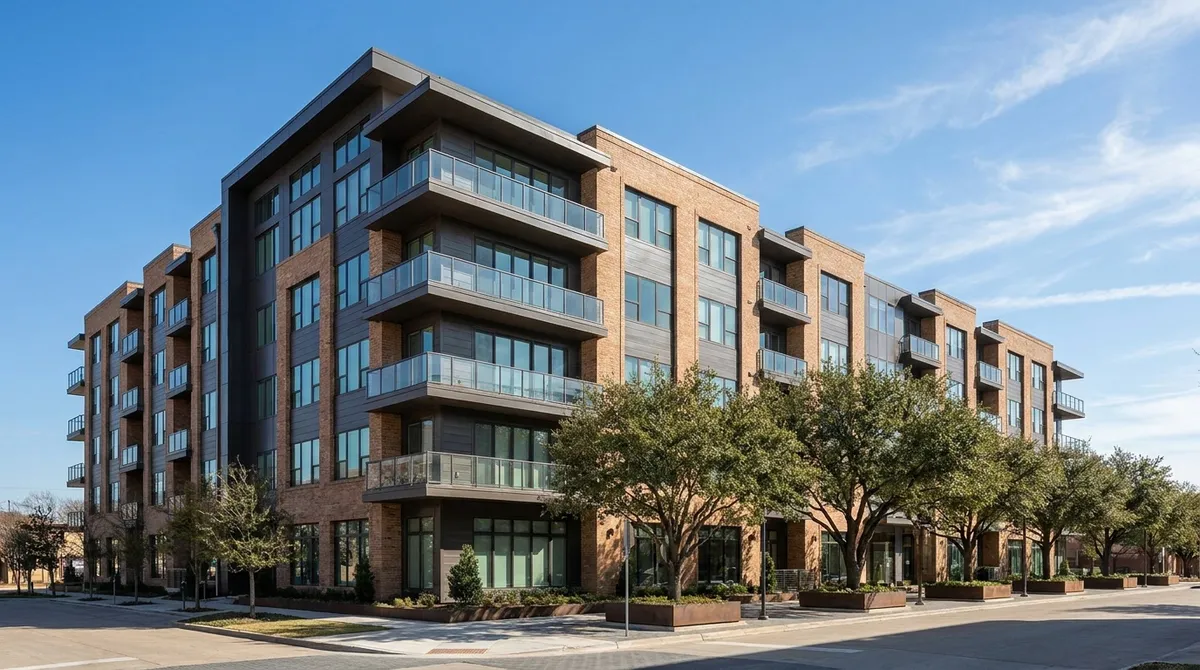
Here’s the straight answer: yes, you can buy a condo in Dallas, Fort Worth with FHA financing, but there’s a catch. The condo building must either be on HUD’s approved list or qualify for Single-Unit Approval. In my experience, most Dallas, Fort Worth condo projects aren’t pre-approved, which means you’ll need a lender who actually knows how to handle the Single-Unit process.
That’s where the real opportunity sits. FHA loans still deliver that 3.5% down payment and competitive rates for condos, and the loan limits in Dallas County cover most condo prices you’ll encounter. I’ve walked 47 first-time buyers through FHA condo purchases, and once you know which boxes to check, the process becomes straightforward.
Book a free 10-minute consultation to map your exact path forward.
FHA Condo Eligibility in Dallas, Fort Worth: How to Know if a Unit Qualifies
You’re smart to check this before falling in love with a property. Not every Dallas, Fort Worth condo qualifies for FHA financing, and as a first-time buyer, knowing this upfront can save you weeks of disappointment and keep your timeline on track. Working with an experienced local agent helps you navigate these requirements from day one, but here’s what you need to know about FHA eligibility (getting either the whole building approved or just your specific unit approved).
How do I check if a Dallas, Fort Worth condo is on the FHA approval list?
Here’s what I tell my clients: start with HUD’s official condo lookup tool. Search by property name or address. If the building shows “Approved” status, you’re golden. If it’s not listed, expired, or rejected, don’t panic. You can still qualify through individual unit approval.
What is Single-Unit Approval, and when would I use it?
Let me put this plainly: unit-specific approval lets you buy a condo with FHA backing even when the entire building isn’t on the approved list. Your lender submits just your unit for approval during the loan process. This works when the building meets basic FHA requirements but hasn’t gone through full project approval.
Which building-level requirements could disqualify a Dallas, Fort Worth condo from FHA eligibility?
The building must be at least 50% owner-occupied and have adequate financial reserves. It needs proper insurance coverage with no major pending litigation. Commercial space can’t exceed 25% of the building. If the HOA has deferred maintenance issues or insufficient reserves, that’s a deal-breaker for FHA backing.
Can I use FHA if most units in the building are rentals?
FHA requires at least 50% owner-occupancy in buildings with more than four units. If 64% of units are investor-owned, that violates the rule and disqualifies the building. Good news, though: buildings with 10 or fewer units don’t face this restriction under current FHA guidelines.
How do special assessments or lawsuits affect FHA qualification for Texas condos?
Pending litigation against the HOA or developer can disqualify a building from FHA eligibility. Special assessments over $1,000 per unit may also create issues. Your lender will review the HOA’s legal status first. Then they’ll check the financial health to spot potential deal-breakers.
What happens if the condo I want isn’t FHA-eligible?
You have three solid options: choose a different unit in an approved building, pursue individual unit approval, or consider conventional financing instead. If I miss any of these eligibility issues during our search, that’s on me, not you. Want me to check a specific Dallas, Fort Worth condo’s FHA status? Text me the address, and I’ll have an answer within 24 hours.
Money Questions: Down Payment, Loan Limits, and Monthly Costs
Let’s talk numbers. When you’re considering FHA financing for a Dallas, Fort Worth condo, you need concrete answers about what you’ll pay upfront, what you can borrow, and how your monthly costs will look. Understanding the FHA loan limits Dallas County sets, and the real costs involved, helps first-time homebuyer FHA Dallas, Fort Worth candidates make confident decisions. Here’s what you need to know:
What are the current FHA loan limits in Dallas County for 2026?
The FHA loan limit for Dallas County in 2026 is $498,257 for a single-unit condo. This means you can finance up to that amount with an FHA loan. If the condo you want costs more, you’ll need a jumbo loan or conventional financing instead.
Is the minimum down payment really 3.5%, and when would 10% be required?
Yes, FHA requires just 3.5% down if your credit score is 580 or higher. If your score falls between 500-579, you’ll need 10% down. For a $400,000 Dallas, Fort Worth condo, that’s either $14,000 or $40,000 upfront, a significant difference.
How do HOA dues affect my debt-to-income calculations?
Your monthly HOA dues get added to your mortgage payment, taxes, and insurance when lenders calculate your debt-to-income ratio. If HOA dues are $300 monthly, that’s $3,600 annually, which counts against how much you can borrow. Higher dues mean you might qualify for a smaller loan amount.
What are the FHA mortgage insurance premiums for condos?
Most condo buyers pay annual premiums around 0.85% of their loan balance monthly, plus an upfront premium of 1.75% of their loan amount at closing. The annual rate can range from 0.45% to 1.05%, depending on your down payment and loan size. Rates can change, so we’ll confirm current premiums during your consultation.
Can I use gift funds or down payment assistance for my FHA condo purchase?
Absolutely. FHA allows 100% of your down payment and closing costs to come from gifts from family members, employers, or approved down payment assistance programs. Dallas, Fort Worth has several first-time buyer programs that work perfectly with FHA financing.
How does my credit score affect my total monthly costs with FHA?
While FHA accepts lower credit scores, a higher score can save you money on interest rates and mortgage insurance. The difference between a 580 score and a 740 score might be $200+ monthly on a $400,000 loan. That’s real money over 30 years.
Ready to see exactly what your numbers look like? I’ll walk you through your specific situation during a free consultation, and if I’m ever late to our appointment, I’ll hand you $100 on the spot. Let’s get your real monthly costs calculated and your path to homeownership mapped out.
The FHA Condo Financing Process: Steps and Timelines
Knowing what happens between your offer acceptance and closing day helps you stay calm and prepared. The FHA financing process for condos has a few extra moving parts compared to single-family homes, but understanding the timeline and requirements keeps you ahead of potential hiccups.
What are the main steps from pre-approval to closing on a Dallas, Fort Worth condo with FHA?
Start with pre-approval, then find your condo and make an offer. Once accepted, your lender orders the appraisal and requests HOA documents. The underwriter reviews everything while you complete your home inspection (which I cover at ~$600 value). Final approval comes after all conditions are met, followed by a clear-to-close and your closing.
How much time does Single-Unit Approval add compared to an already-approved project?
Single-Unit Approval adds 2-4 weeks to your timeline since your lender must submit the unit for individual HUD review. An FHA-approved project from the HUD database moves at normal speed, typically 30-45 days total. HUD processes requests within 30 days, but gathering documents takes additional time upfront.
Which HOA documents will my lender need, and how can I speed this up?
Your lender needs the HOA budget, reserve study, insurance certificates, and a completed questionnaire. Contact the HOA management company immediately after your offer is accepted. Don’t wait for your lender to request them. Many HOAs charge fees and take 7-10 business days, so early action prevents delays.
Could low HOA reserves cause FHA approval problems?
Yes, insufficient reserves can derail your loan. FHA requires adequate funding for maintenance and repairs. If reserves are below 10% of the annual budget, your lender might require additional documentation or deny the loan. Some buildings address this by increasing HOA dues or implementing special assessments.
How do FHA condo appraisals differ from conventional loans?
FHA appraisers must verify the project meets HUD guidelines, not just the unit value. They check owner-occupancy ratios, commercial space limits, and litigation status. This extra scrutiny can add 3-5 days to the appraisal timeline, but it protects you from buying into a financially unstable building.
What commonly delays FHA condo closings in Dallas, Fort Worth?
Missing HOA documents cause the most problems, followed by appraisal complications and last-minute project approval issues. Stay proactive by confirming your building’s FHA status early and requesting HOA documents immediately. I handle these coordination details and back it with my earnest money guarantee. If something goes wrong, I write the check.
Get Clear, Get Approved, Get Home
Yes, you can buy a Dallas, Fort Worth condo with FHA financing, but success depends on checking the HUD database first or pursuing Single-Unit Approval. You can get started with just 3.5% down, but HOA financials, owner-occupancy rules, and paperwork make the difference between a straightforward process and costly delays.
Here’s what that means for you as a first-time homebuyer, FHA Dallas, Fort Worth candidate: you deserve an agent who knows these condo-specific hurdles inside and out. I provide paid home inspection ($600 value), lender-paid appraisal ($600 value), earnest money guarantee, $500 moving credit, and a cancel-anytime policy, because your peace of mind matters more than my commission.
Ready to plan your FHA condo purchase with zero risk and maximum clarity? Book your free Initial Consultation and bring a short list of Dallas, Fort Worth condos you’re considering. We’ll walk through each step, check eligibility, review your financing options, and create a timeline that gets you home without the guesswork.
Frequently Asked Questions
How do I check if a Dallas, Fort Worth condo is on the FHA approval list?
Here's what I tell my clients: start with HUD's official condo lookup tool. Search by property name or address. If the building shows "Approved" status, you're golden. If it's not listed, expired, or rejected, don't panic. You can still qualify through individual unit approval.
Is the minimum down payment really 3.5%, and when would 10% be required?
Yes, FHA requires just 3.5% down if your credit score is 580 or higher. If your score falls between 500-579, you'll need 10% down. For a $400,000 Dallas, Fort Worth condo, that's either $14,000 or $40,000 upfront, a significant difference.
How do HOA dues affect my debt-to-income calculations?
Your monthly HOA dues get added to your mortgage payment, taxes, and insurance when lenders calculate your debt-to-income ratio. If HOA dues are $300 monthly, that's $3,600 annually, which counts against how much you can borrow. Higher dues mean you might qualify for a smaller loan amount.
What are the main steps from pre-approval to closing on a Dallas, Fort Worth condo with FHA?
Start with pre-approval, then find your condo and make an offer. Once accepted, your lender orders the appraisal and requests HOA documents. The underwriter reviews everything while you complete your home inspection (which I cover at ~$600 value). Final approval comes after all conditions are met, followed by a clear-to-close and your closing.
What commonly delays FHA condo closings in Dallas, Fort Worth?
Missing HOA documents cause the most problems, followed by appraisal complications and last-minute project approval issues. Stay proactive by confirming your building's FHA status early and requesting HOA documents immediately. I handle these coordination details and back it with my earnest money guarantee. If something goes wrong, I write the check.
Related Articles
Closing Costs in Fort Worth, Texas: What Buyers Pay
Buyer closing costs in Fort Worth run 3% to 5% of the price. The line items one at a time on the median, who pays what in Texas, and how to cut the number.
Down Payment Assistance in Texas: HAP, TSAHC, TDHCA
Texas down payment assistance is not free money. Most of it is priced into your interest rate. The real math on HAP, TSAHC, and My First Texas Home.
FHA vs. Conventional Loan in Texas: Which Is Better?
FHA or conventional in Texas? Compare 2026 down payments, credit minimums, MIP vs PMI, and Tarrant County loan limits with real Fort Worth payment math.